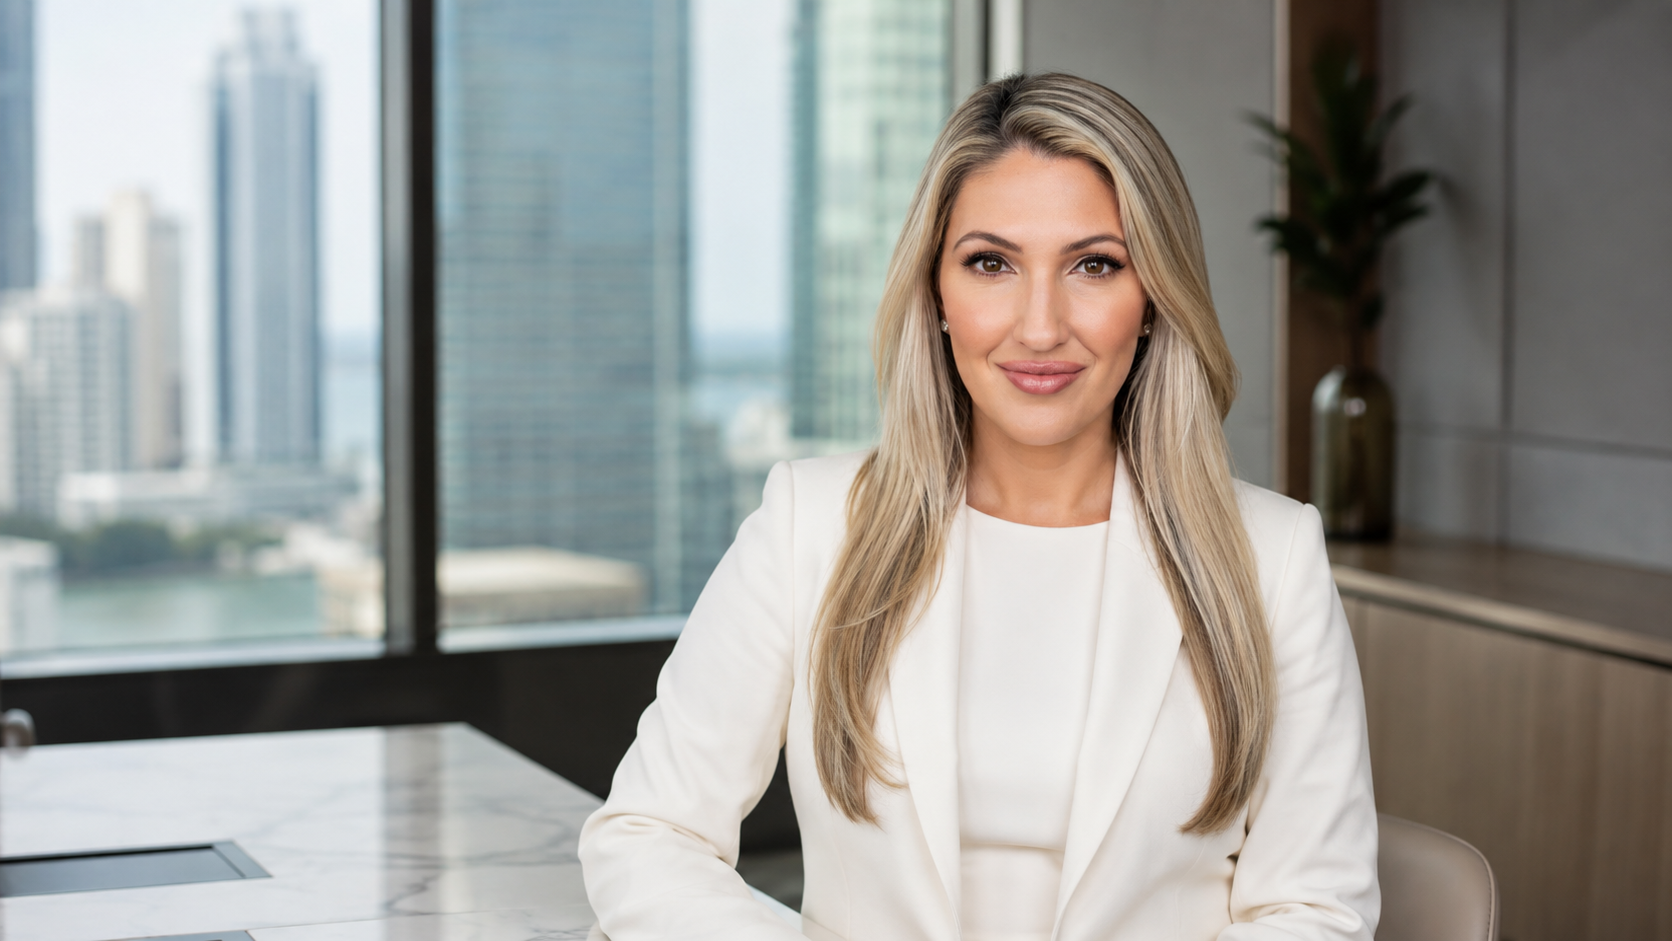
With more than two decades in banking, the City National Bank of Florida vice president believes growing companies need more than financial products—they need an accessible banker who understands their business.
As technology continues to reshape financial services, banking has become faster, more automated and increasingly impersonal. For Elizabeth Fonseca, Vice President and Business Banker at City National Bank of Florida, technology may improve how banking services are delivered, but it should never replace the relationship between a business owner and a trusted financial professional.
“A relationship is between people—not you and an 800 number,” Fonseca told a group of local business professionals during a recent presentation.
That belief has guided a banking career spanning more than 20 years. A Miami native and graduate of Florida International University, Fonseca grew up with banking as part of her family’s story. Her mother spent approximately 45 years in the industry, providing an early example of the importance of service, consistency and trust.
Fonseca eventually followed a similar path, building her career around helping business owners understand and address their financial needs. Today, she works with companies seeking banking services, access to capital and treasury-management tools to support their operations and growth.
She is also the mother of two daughters, whom she describes as a constant source of motivation and inspiration.
A Banker Who Understands the Local Market
Business owners often encounter important financial decisions at defining moments: purchasing a company, acquiring commercial property, hiring employees, investing in equipment or securing additional working capital.
Fonseca’s role is to help clients evaluate available banking solutions based on their circumstances and objectives.
Her connection to Miami is an important part of that work. Having grown up in the community, she understands the local marketplace, its cultural diversity and the relationship-driven nature of doing business in South Florida.
She also maintains an active presence in professional and community organizations, including a longstanding involvement with BNI. For Fonseca, networking is not simply a business-development activity. It is a way to remain connected to the professionals, entrepreneurs and families who shape the community she serves.
Her approach reflects a straightforward idea: before recommending a banking solution, a banker should understand the client’s business, challenges and plans.
What Growing Businesses Need From Their Bank
Business banking extends well beyond opening a checking account. A growing company may need tools to receive payments, manage expenses, protect against fraud, maintain liquidity and finance expansion.
Fonseca works with clients across several areas of business banking, including:
- Commercial checking and money-market accounts
- Savings accounts and certificates of deposit
- Digital and mobile banking
- Treasury-management services
- Lines of credit and term loans
- Owner-occupied commercial real-estate financing
- Investment-property financing
- Equipment leasing
- Warehouse financing
- Letters of credit
Treasury management can be particularly important for businesses experiencing growth. Services involving receivables, payables, liquidity, merchant processing, fraud protection and financial-information management may help an organization exercise greater control over its cash flow and daily financial operations.
The appropriate combination of services will differ from one company to another. Fonseca emphasized that banking should not be approached as a standardized package in which every business receives the same products. Her objective is to identify solutions that correspond to the client’s actual needs.
That consultative approach becomes especially valuable when businesses are preparing for their next stage of development.
Recognizing an Ideal Referral
Fonseca’s ideal client is often a business owner approaching a transition or growth opportunity.
That could be someone who is:
- Purchasing or expanding a business
- Buying an office, warehouse or other commercial property
- Seeking working capital
- Hiring additional employees
- Investing in equipment
- Attempting to improve cash-flow management
- Frustrated with high fees, poor service or slow decisions at another financial institution
- Looking for direct access to a local banking relationship
CPAs, attorneys, payroll providers, real-estate professionals and other business owners are among the referral partners most likely to recognize these situations.
The need does not always begin with a loan request. Sometimes the first indication is operational: a company is growing, its transactions are becoming more complex or its existing banking structure no longer supports the way it conducts business.
A knowledgeable banker can help the owner identify questions that should be addressed before the company’s needs become urgent.
The Value of Local Decision-Making
City National Bank of Florida was founded in Miami in 1946 and describes its operating philosophy through three principles: personal relationships, local decisions and stability.
For business owners, local decision-making can provide an important connection between a company’s financial request and the market in which it operates. Fonseca explained that clients can work with bankers and decision-makers who understand Florida’s business environment instead of relying exclusively on a distant service center.
The bank’s broader business platform includes commercial banking, real-estate lending, private banking, wealth management, international banking, treasury management, corporate services and capital-markets capabilities.
According to the bank, City National Bank of Florida had approximately $29 billion in assets as of March 31, 2026. It also reported a five-star “Superior” rating from BauerFinancial based on information available as of June 30, 2025. The institution is headquartered in Miami and serves clients across South and Central Florida.
Yet Fonseca’s message was less about the institution’s size than about how those resources are delivered. The central promise is that clients receive a relationship manager supported by specialists who can help address different aspects of their financial needs.
Expanding Access Through SBA Financing
During her presentation, Fonseca invited Armand Martinez, a senior banking and small-business-financing professional, to discuss the U.S. Small Business Administration’s 504 loan program and how banking institutions can work with Certified Development Companies.
The SBA 504 program provides long-term, fixed-rate financing for qualifying major fixed assets that support business growth and job creation. Eligible uses may include owner-occupied commercial real estate, construction and certain heavy machinery or equipment.
A typical SBA 504 financing structure may include a senior loan from a private-sector lender covering up to 50% of eligible project costs, a junior lien associated with a Certified Development Company covering up to 40%, and a borrower equity contribution of at least 10%. The required contribution may be higher depending on the business, project and applicable SBA requirements.
The program generally does not finance working capital or inventory. Those needs may be addressed through other conventional or SBA-supported banking solutions when available and appropriate.
The discussion illustrated the value of collaboration. A business banker does not need to serve as the only expert involved in a transaction. The banker can coordinate with internal specialists, outside financial professionals and qualified development organizations when a client’s plans require specialized knowledge.
Relationship Banking as a Business Strategy
The strongest banking relationships are often established before a company urgently needs financing.
When bankers understand how a business earns revenue, manages expenses and plans for growth, they can provide more relevant guidance as circumstances change. Business owners, in turn, are better positioned to understand what financial records, planning and preparation may be required when an opportunity emerges.
Fonseca’s approach is rooted in accessibility: know your banker, communicate before a major decision and treat banking as an ongoing business relationship rather than an occasional transaction.
In an industry increasingly shaped by automation, that personal connection may be one of the most valuable services a financial institution can provide.
For Miami’s entrepreneurs, Fonseca’s message is clear: the right banking relationship should do more than hold a company’s money. It should help the business owner ask better questions, prepare for opportunities and make informed financial decisions.
Important disclosures: This article is for general informational purposes only and does not constitute financial, legal, tax or accounting advice. Banking products, credit facilities and loan programs are subject to applicable eligibility requirements, credit approval, program guidelines, fees, restrictions, terms and conditions. Terms and availability are subject to change. Not all products or programs are available to every applicant or in every location. Deposit products are offered by City National Bank of Florida, Member FDIC. Loan products are not FDIC insured and are not guaranteed by the bank or the federal government unless expressly provided under an applicable government program. City National Bank of Florida is an Equal Housing Lender. NMLS #412469. SBA loan programs are administered under applicable SBA requirements and do not represent a commitment to lend. City National Bank of Florida does not provide tax, legal or accounting advice.