Select Page

Communities

Widgetized Area

This panel is active and ready for you to add some widgets via the WP Admin

Home repairs in North Bay Village

Home repair work can range from a small fix to a larger project that affects several parts of a property. North Bay Village residents, property owners, and organizations can use this page to find and compare home repair providers in the area. Treat each listing as a starting point: contact the provider directly to confirm the current service area, availability, qualifications, and terms before choosing a service.

Home repairs services to explore

Depending on the provider, providers may handle general maintenance, carpentry, fixture replacement, drywall, painting, installation, or other repair requests. Some businesses focus on one specialty, while others offer several services through a single office. Ask which work is performed by the provider, what is handled by a partner, and whether the service is available for your particular project or situation. A clear description of the work helps you compare providers on similar terms.

How to compare home repairs providers

Start with the need, location, timing, and budget you have in mind. Request a written scope or explanation of what is included, how long the work may take, and what could affect the final cost. Compare experience with similar requests, communication practices, scheduling, payment terms, and the process for follow-up. If credentials, permits, insurance, or a written agreement apply to the service, ask for current details and verify them with the appropriate source.

Questions to ask before you decide

Ask what is included in the estimate, whether a site visit is needed, who supplies materials, how changes are approved, and what documentation or follow-up is provided. Review the answer alongside the provider’s listing and written terms. Ask for clarification if a service description is broad, a quote leaves out important work, or a timeline is uncertain. Confirm how to reach the business after the initial appointment and what steps are available if the service needs correction or further attention.

Find home repairs in North Bay Village

Browse the North Bay Village business directory to identify local listings and request current information. Compare providers using the same criteria so differences in scope, availability, and price are easier to understand. A directory listing is not an endorsement, and details should be verified directly with each business.

For municipal contacts and community information, visit the official North Bay Village website. Contact providers directly to confirm the details that matter for your needs and keep written estimates, policies, and agreements for reference.
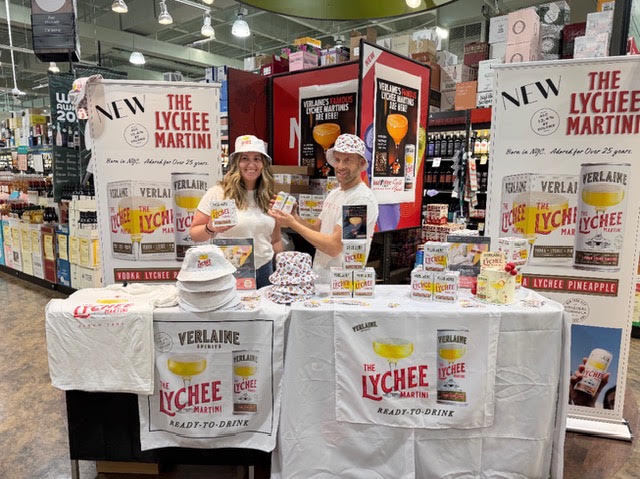
From the Lower East Side to South Beach: Verlaine’s Lychee Martini Makes a Splash at Total Wine

The ready-to-drink version of a New York City favorite earned a manager’s pick at Total Wine & More in South Beach, where shoppers snapped up the four-packs reserved for a weekend tasting.
A taste of New York City has made its way to Miami Beach, and for some shoppers, it brought a little nostalgia.
During a recent tasting at Total Wine & More in South Beach, a couple visiting from New York City spotted a familiar name on the shelves: Verlaine Lychee Martini. Regulars at Verlaine Bar & Lounge on Manhattan’s Lower East Side, the couple recognized the cocktail they had enjoyed back home and picked up a four-pack.
They weren’t the only ones intrigued. Throughout the event, shoppers stopped to sample the canned cocktail, with some recognizing the iconic New York bar and others discovering its signature drink for the first time. By the end of the tasting, the four-packs reserved for the event had sold out.
The cocktail remains available for purchase at the South Beach location.
A New York Favorite Gets a South Beach Welcome
The Verlaine Lychee Martini received a warm welcome from the South Beach store’s general manager, Sharmila Vernon, who selected it as one of her personal favorites.
A shelf display featuring Vernon’s photo and the words “Sharmila’s Favorite” highlighted the cocktail alongside its distinctive white packaging, featuring an illustration of a golden lychee martini.
Priced at $12.99 for a four-pack, the ready-to-drink cocktail comes in 250-milliliter cans with 13.4% alcohol by volume, offering customers a convenient way to enjoy the bar’s signature cocktail without mixing one themselves.
 
The tasting brought a festive atmosphere to the store, with towering Verlaine Lychee Martini banners, bold red and yellow branding, and stacks of four-packs surrounding the sampling
Local bakery, Sweet T Cakery, made a custom cake to celebrate the tasting.
station. Branded T-shirts and bucket hats also caught shoppers’ attention, adding to the excitement surrounding the launch.
Guests had the opportunity to sample the cocktail before purchasing, while local bakery Sweet T Cakery created a custom cake to commemorate the occasion.
 
From a Lower East Side Institution to a Ready-to-Drink Cocktail
The story of Verlaine’s Lychee Martini began in 2001 at Verlaine Bar & Lounge, a longtime fixture of Manhattan’s Lower East Side nightlife scene.
Made with vodka, lychee and pineapple, the cocktail quickly became the bar’s signature drink, developing a loyal following among New Yorkers and visitors alike. According to the producer, the lounge serves more than 12,000 lychee martinis each month, a testament to the drink’s enduring popularity.
Now, more than two decades later, Verlaine Spirits is bringing that same recognizable flavor beyond the bar through its canned, ready-to-drink version. The spirits company operates independently of the original New York lounge.
The South Beach tasting marked another opportunity to introduce the cocktail to a new audience while reconnecting with customers already familiar with its New York roots.
For Verlaine Spirits, the enthusiastic response offered an encouraging sign of the cocktail’s potential in South Florida, where a thriving hospitality scene and year-round cocktail culture make Miami Beach a natural market for the brand.
And for New Yorkers who find themselves in South Beach, a familiar Lower East Side favorite is now just a four-pack away.
Learn more: thelycheemartini.com

Read More

The Friday Cash-Flow Review Every Growing Business Needs

“A weekly cash-flow review makes the next business decision visible before the bank balance makes it urgent.”
By Wilson Alvarez
Quick answer: Review expected cash receipts and payments every week across the next 13 weeks. Start with current available cash, update invoices by realistic collection date, include payroll, taxes, rent, debt and planned purchases, then decide who owns each action before a gap becomes a crisis.
“Where focus goes, energy flows.” — Tony Robbins
Robbins’s observation is especially practical for a company’s financial rhythm. When an owner looks at cash only after an account feels tight, attention becomes reactive. A scheduled review directs energy toward collection conversations, spending choices and capacity planning while there is still time to act. Focus does not create cash by itself; it helps the company make earlier, better decisions. Source: Tony Robbins.
Why a profitable business can feel cash-poor
A firm can record a sale in one month, pay its people the next week and collect from the customer much later. That timing gap can strain an otherwise healthy operation. In Miami, seasonal demand, tourism cycles, construction schedules and event-driven work can make the gap more noticeable. A new contract may be welcome, but it can require deposits, labor and equipment before the first payment arrives.
The income statement answers whether revenue exceeded expenses over a period. A cash forecast answers whether money will be available on the dates bills come due. Owners need both views. The U.S. Small Business Administration emphasizes financial records and cash-flow projections in managing a business. See SBA guidance. A coach can help the owner build a decision routine around those records, while an accountant can help ensure the underlying numbers are sound.
Build a simple 13-week view
Begin with available cash at the start of this week. Add expected receipts by week, using the date you reasonably expect to collect rather than the invoice due date if a customer has a consistent payment pattern. Subtract payroll, payroll obligations, rent, vendor payments, loan obligations, taxes and other known outflows. Carry the ending balance into the next week. Repeat through week 13. This rolling horizon is long enough to expose a near-term gap and short enough to update from real information.
Keep the model understandable. List large receipts separately and group smaller recurring receipts. Mark uncertain items so no one confuses a verbal promise with a deposit. Include committed expenses even if the invoice has not arrived. If a planned purchase is discretionary, identify it clearly. The forecast is a management tool, not a polished display of certainty that does not exist.
Run the Friday review
Choose a consistent day and invite the owner, finance lead and the person responsible for collections or major accounts. Compare last week’s forecast with actual deposits and payments. Ask why an expected payment did not arrive and whether it moved one week or became genuinely uncertain. Check the lowest projected cash balance over the horizon, not just the ending week. Note upcoming payroll and tax dates as fixed commitments.
Then make a short action list. One person may confirm a customer’s payment date. Another may send a milestone invoice immediately after approval. The owner may postpone a nonessential purchase or negotiate a vendor schedule before a bill is overdue. Record the person and date for each action. The next meeting begins by checking what happened, not by rebuilding the same conversation from memory.
Improve the cash conversion cycle
Forecasting reveals symptoms; process changes address causes. Examine the time from accepted work to invoice, from invoice to collection, and from purchase to delivery. Are proposals clear about deposits and milestone billing? Does the team wait until month-end to bill completed work? Are invoices missing purchase order details? Do client approvals sit in someone’s inbox? Fixing an administrative delay can release cash without adding sales.
For a Miami marketing firm, a project might move from a single payment at completion to a deposit, a production milestone and a final invoice. For a distributor, inventory purchasing and customer terms may be the central issue. For a restaurant group, weekly payroll and supplier timing may matter more. The model must reflect the economics of the actual business. Do not copy another firm’s assumptions just because its spreadsheet looks polished.
Use scenarios without pretending to predict the future
Create a base case and a cautious case. What happens if a large invoice arrives two weeks late, a project is delayed or sales fall temporarily? What expense can be paused, and what obligation cannot? A scenario is useful when it identifies a decision trigger: “If cash falls below this reserve threshold by week six, we delay the equipment purchase and review staffing capacity.” Discuss financing options with appropriate advisors early if a gap persists. Do not treat borrowing as a substitute for a weak margin or chronic late billing.
Protect trust while collecting
Collections should be firm and professional. Confirm terms at the outset, invoice promptly and follow up with a clear record. A client may have a legitimate dispute that requires resolution, or may simply need the correct paperwork. Preserve the relationship while asking for a precise payment commitment. A forecast that repeatedly assumes payment without evidence is not a forecast; it is wishful thinking.
Frequently asked questions
Why review cash flow weekly instead of monthly?
Weekly review gives an owner time to address delayed receipts or upcoming obligations before a month-end report arrives. The frequency is especially valuable when payroll and vendors are due on fixed dates.
How accurate must the forecast be?
It should be transparent about assumptions and updated from actual results. The goal is useful decisions, not a false claim of perfect prediction.
Does a positive profit figure mean cash is safe?
No. Receivables, inventory, debt payments and timing can create a cash gap even when the income statement shows profit.
Miami business owners who want to strengthen their leadership, visibility and growth strategy can connect with Wilson Alvarez at walvarez@miamibusiness.com or 305-386-6165.

Read More

Association Lending Services: Finding Financing Solutions When Traditional Banks Say No

From South Florida to New York, principal Sachin Mehrotra and business development professional Errol Eisinger are helping condominium associations explore financing opportunities that conventional lenders may be unwilling or unable to accommodate.

For condominium associations throughout South Florida, the challenge of maintaining aging buildings has become increasingly complicated. Rising construction costs, escalating insurance premiums, structural restoration requirements, and the financial demands of major capital improvements have placed significant pressure on condominium boards and the property owners they represent. What might once have been a relatively straightforward building improvement project can now require millions of dollars in financing, extensive financial documentation, and difficult decisions about how those costs will be shared among residents.
The situation becomes particularly challenging when an association approaches its existing financial institution only to discover that the proposed transaction falls outside the bank’s lending guidelines. Pending litigation, limited reserves, high rental occupancy, or unusual property characteristics can complicate an otherwise legitimate financing request. For association boards already confronting urgent repair deadlines, the inability to secure financing can create uncertainty about how to move forward.
Yet a rejection from one lender does not necessarily mean that every financing option has been exhausted. That distinction is at the center of the business philosophy behind Association Lending Services, a Florida-based company specializing in financing solutions for condominium associations, homeowners associations, and other community associations. Led by principal Sachin Mehrotra, with Errol Eisinger overseeing business development and client relationships, the company focuses on evaluating complex financing opportunities and identifying lenders whose underwriting requirements may accommodate transactions that traditional institutions have declined.
The First Call or the Last Call: A Different Approach to Association Financing
In commercial lending, experience often becomes most valuable when a transaction does not fit neatly within established underwriting guidelines. Traditional financial institutions operate within specific lending parameters designed to manage risk, maintain portfolio standards, and ensure that borrowers meet defined financial requirements. While those standards serve an important purpose, they can also limit the options available to condominium associations whose circumstances fall outside conventional expectations.
Mehrotra approaches these situations from a different perspective. His philosophy is that Association Lending Services should be either the first call an association makes when considering financing or the last call after other lenders have been unable to provide a solution. Rather than evaluating a transaction solely through the limitations of one institution, the company examines the broader financial picture, the association’s repayment capacity, and the financing structures that may be available through specialized lending relationships.
That approach does not mean every financing request can be approved. It means that an association’s circumstances deserve a thorough evaluation before its financing possibilities are dismissed. Understanding why a traditional lender declined a transaction can be just as important as identifying the institutions that may be willing to consider it.
For condominium boards responsible for protecting substantial real estate assets and representing hundreds of property owners, that distinction can be significant. A financing professional who understands both the banking environment and the operational realities of community associations may be able to identify alternatives that were not considered during the initial application process.
A $2.3 Million Brooklyn Transaction Demonstrates the Company’s Reach
Although Association Lending Services is based in Florida, its financing activities extend beyond the state’s borders. One notable example involved a condominium association in Brooklyn, New York, where the company helped facilitate a reported $2.3 million financing transaction associated with major building improvements and related financial obligations.
The transaction illustrates the complexity that can arise when an association must address substantial capital requirements while navigating financial circumstances that may concern conventional lenders. Rather than treating the financing request as an isolated loan application, specialized association lending requires consideration of the property’s financial condition, its existing obligations, its ability to collect assessments, and the proposed repayment structure.
For associations confronting significant building repairs, financing can provide an alternative to collecting the entire project cost through an immediate special assessment. Depending on the terms of the transaction, an association may be able to spread repayment obligations over an extended period, potentially providing greater financial predictability for participating owners. Borrowing does not eliminate the cost of the project, however, and interest, fees, and repayment obligations must be evaluated carefully.
The Brooklyn transaction also received independent media attention. In October 2026, journalist Emily Myers reported on the financing arrangement for Habitat Magazine, examining the condominium’s financial challenges and the involvement of Association Lending Services.
Readers interested in the original reporting can review Habitat Magazine’s coverage of the $2.3 million Brooklyn condominium financing transaction.
For South Florida condominium boards, the broader significance lies in understanding that difficult financing circumstances do not always produce identical outcomes across different lending institutions. A transaction that falls outside one lender’s preferred criteria may warrant consideration by another institution with a different underwriting strategy.
When Rental Occupancy Becomes a Financing Obstacle
One of the less frequently discussed challenges in condominium association financing involves investor concentration. In communities where a substantial percentage of units are rented rather than owner-occupied, some lenders may impose additional underwriting requirements or decline transactions that exceed their preferred rental-occupancy thresholds.
The reasoning is largely connected to risk assessment. Lenders may examine whether an association can consistently collect assessments, maintain sufficient operating revenue, and meet its financial obligations under different economic conditions. A high percentage of investor-owned units can influence that evaluation, although the significance varies according to the lender, the association’s financial condition, and the type of financing requested.
Association Lending Services reports having facilitated financing for two condominium projects with approximately 95% rental occupancy, a concentration that can present challenges for certain traditional lending institutions. These transactions, as described by the company, demonstrate why specialized financing relationships can be particularly valuable when conventional underwriting requirements limit the available options.
There is no universal rule that prohibits every condominium association with more than 25% rental occupancy from obtaining financing. Individual lenders establish their own criteria, and different loan products may apply different standards. The relevant question is whether an association’s financial strength, repayment capacity, and overall risk profile satisfy the requirements of a lender willing to consider the transaction.
For Mehrotra, the objective is not simply to locate a lender offering attractive terms. It is to identify institutions capable of evaluating the particular circumstances of the association and determining whether a responsible financing structure is available.
Why Experience and Relationships Still Matter in Modern Lending
Technology has dramatically changed how borrowers research financing options, prepare applications, and communicate with financial institutions. Digital platforms can streamline documentation, accelerate preliminary evaluations, and provide access to information that once required numerous telephone calls and in-person meetings. Yet complex lending transactions continue to depend on professional judgment, experience, and established relationships.
Eisinger brings more than five decades of experience in commercial lending and real estate to Association Lending Services. His professional background, combined with his experience serving on a condominium association board, provides a perspective that connects the financial requirements of lending institutions with the practical responsibilities facing association directors.
Board members are not simply borrowing money. They are making decisions that may affect property values, monthly assessments, reserve balances, and the long-term financial obligations of their communities. Those decisions require an understanding of financing alternatives, repayment structures, project timelines, and the potential consequences of delaying necessary improvements.
Through business development and client relationships, Eisinger helps connect association representatives with the resources and expertise needed to explore those decisions. Mehrotra’s specialized financing experience complements that work by focusing on the evaluation and structuring of transactions that may require more extensive lender engagement.
The combination illustrates an important reality of commercial finance: Technology may improve the efficiency of the process, but understanding the people, properties, and financial circumstances behind a transaction remains essential.
What South Florida Condominium Associations Can Learn
For condominium boards in Miami-Dade, Broward, and Palm Beach counties, the need to evaluate financing alternatives has become increasingly relevant. Florida’s evolving condominium inspection and reserve requirements, combined with the costs associated with maintaining older buildings, have placed greater attention on long-term capital planning and the financial responsibilities of association leadership.
Some communities may have sufficient reserves to fund necessary improvements without borrowing. Others may determine that a special assessment, an association loan, or a combination of funding sources is more appropriate. The correct approach depends on the association’s financial condition, governing documents, project requirements, applicable laws, and the terms available from prospective lenders.
Financing can offer flexibility, but it should never be mistaken for eliminating a financial obligation. When an association borrows money, repayment generally becomes part of its financial planning, and owners may ultimately bear those costs through regular or special assessments. Interest expenses, loan fees, repayment periods, and other contractual obligations must be considered alongside the immediate benefits of obtaining capital.
Associations can improve their readiness for financing discussions by maintaining accurate financial statements, current budgets, reliable assessment collection records, and clear documentation of proposed projects. Understanding the association’s existing obligations and anticipated future expenses can also help lenders evaluate its repayment capacity.
Perhaps most importantly, boards should recognize that different lenders may view the same transaction differently. Exploring appropriate alternatives can be a responsible part of the decision-making process, particularly when a major project cannot be postponed indefinitely.
The Value of Looking Beyond the First Rejection
The experience of Association Lending Services illustrates a broader lesson about specialized commercial finance. Complex transactions are rarely defined by a single financial metric, and an initial rejection does not always provide a complete picture of the available lending market.
A condominium association may have unusual rental concentration, pending legal matters, significant capital requirements, or other characteristics that make conventional financing more difficult. Those circumstances require careful analysis, but they do not necessarily eliminate every potential lending relationship.
The challenge is determining whether the association has the financial capacity to support a loan and whether an institution exists whose lending criteria appropriately accommodate the transaction. That process requires both a realistic understanding of risk and familiarity with the financial institutions willing to evaluate specialized opportunities.
For Sachin Mehrotra and Errol Eisinger, that is the business behind Association Lending Services: helping associations explore financing possibilities when the path forward is not immediately apparent.
In a market where aging infrastructure, capital improvement requirements, and financial pressures continue to challenge community associations, the ability to examine complicated transactions from multiple perspectives may prove increasingly valuable.
Exploring Financing Options With Association Lending Services
Condominium and homeowners association boards considering major repairs, capital improvements, structural restoration, or other substantial financial obligations can benefit from reviewing available financing alternatives before committing to a particular course of action.
Errol Eisinger and the Association Lending Services team work with association representatives to discuss project requirements, evaluate financing opportunities, and identify potential lending relationships appropriate to the circumstances.
Whether an association is beginning its financing search or has already encountered challenges with traditional lenders, an informed discussion can help clarify the options that may be available.
Errol Eisinger
Association Lending Services
Phone: 786-205-9842
Email: eeisinger@associationfinancing.org
Website: www.associationlendingservices.com
Financing is subject to lender underwriting, eligibility requirements, documentation, credit approval, and applicable terms and conditions. Loan availability, interest rates, repayment structures, and closing timelines vary by transaction and jurisdiction. Association Lending Services does not guarantee loan approval, financing amounts, or funding timelines. Associations should consult their legal and financial advisers before entering into financing agreements.

Read More

Emerging Company Intelligence Report — April 2026

This April 2026 edition of MiamiBusiness.com reviews funding activity from March 2026 and the signals it offers Miami investors.
April 2026 Investor Intelligence
March 2026 funding rounds brought more than $915 million into seven private technology companies. This retrospective examines the financing, investment implications and Florida connections.
TL;DR: March 2026 — Seven Major Technology Funding Rounds
Miami Business reports on seven private technology companies that closed significant funding rounds in March 2026. Armadin ($189.9M), XBOW ($120M), TENEX.AI ($250M), Qodo ($70M), Linx Security ($50M), Glimpse ($35M), and Eridu ($200M) collectively raised over $915 million.
Historical Retrospective: Published November 2026
This report is published as a historical retrospective in November 2026, documenting verified private technology company funding announcements made strictly during the March 1–31, 2026 period. Research cutoff: March 31, 2026. All amounts, investors, and company details reflect contemporaneous public disclosures.
Table of Contents

Armadin — $189.9M Seed + Series A
XBOW — $120M Series C
Qodo — $70M Series B
TENEX.AI — $250M Series B (Sarasota, FL)
Linx Security — $50M Series B
Glimpse — $35M Series A (a16z-backed)
Eridu — $200M Series A (from Stealth)
Institutional Investor Implications
Due Diligence Risks
Miami Relevance
FAQ
Financial Disclaimer

1. Armadin — $189.9M Seed and Series A (Announced March 10, 2026)
Sector: Cybersecurity / AI-driven threat detection HQ: Not publicly established as Miami-based Website: armadin.com Official Funding Announcement: Armadin Secures Record-Breaking $189.9M in Seed and Series A
Armadin raised a combined $189.9 million across seed and Series A rounds, announced March 10, 2026. The company builds AI-driven cybersecurity infrastructure designed to combat “hyperattacks” — coordinated, large-scale cyber incidents that overwhelm traditional defenses. The dual-round structure suggests a strategic scaling play to accelerate product development and market expansion.
Investors: Details per Armadin’s official announcement. Public Contact: Not publicly available.
2. XBOW — $120M Series C (Announced March 18, 2026)
Sector: Space technology / Spacecraft systems HQ: Not publicly established as Miami-based Website: xbow.com Official Funding Announcement: XBOW Raises $120M to Scale
XBOW, a spacecraft manufacturer, closed a $120 million Series C round announced March 18, 2026. The company designs and produces modular spacecraft and satellites for commercial and government applications. The Series C indicates XBOW has progressed past early-stage validation into production-scale operations.
Investors: Details per XBOW’s official announcement. Public Contact: Not publicly available.
3. Qodo — $70M Series B (Announced March 30, 2026)
Sector: AI / Software development tools HQ: Not publicly established as Miami-based Website: qodo.ai Official Funding Announcement: Qodo $70M Series B: Shift to Artificial Wisdom
Qodo announced a $70 million Series B round on March 30, 2026, framing its investment around a strategic pivot toward “artificial wisdom” — moving beyond narrow AI capabilities toward broader, more reasoned software development assistance. The company builds AI tools for software engineering workflows.
Investors: Details per Qodo’s official announcement. Public Contact: Not publicly available.
4. TENEX.AI — $250M Series B (Announced March 31, 2026)
Sector: Artificial intelligence / Quantum-AI computing HQ: Sarasota, Florida (Sarasota, FL) Website: tenex.ai Official Funding Announcement: TENEX.AI Series B
TENEX.AI closed the largest single-round deal of the month — a $250 million Series B announced March 31, 2026. The company develops next-generation AI and quantum computing infrastructure. TENEX.AI is the only company in this report with a verified Florida headquarters (Sarasota, FL), making it directly relevant to Miami’s growing technology ecosystem.
Investors: Details per TENEX.AI’s official announcement. Public Contact: Not publicly available.
5. Linx Security — $50M Series B (Announced March 31, 2026)
Sector: Cybersecurity / Supply chain security HQ: Not publicly established as Miami-based Website: linx.security Official Funding Announcement: Linx Security Raises $50M Series B
Linx Security secured $50 million in a Series B round announced on March 31, 2026. The company provides supply chain security solutions, protecting software integrity from development through deployment. The timing — announced the same day as TENEX.AI’s deal — marks a pair of major March announcements in the security sector.
Investors: Details per Linx Security’s official announcement. Public Contact: Not publicly available.
6. Glimpse — $35M Series A (Announced March 25, 2026)
Sector: Consumer goods technology / Dispute tracking HQ: Not publicly established as Miami-based Website: Company official site verified via TechCrunch source Official Source: a16z-Backed Glimpse Raises New Funds (TechCrunch, March 25, 2026)
Glimpse raised $35 million in a Series A round announced March 25, 2026. Backed by a16z (Andreessen Horowitz), the company builds dispute-tracking automation tools for consumer packaged goods (CPG) brands. The a16z backing provides notable institutional validation.
Investors: Andreessen Horowitz (a16z) — verified per TechCrunch source. Public Contact: Not publicly available.
7. Eridu — $200M Series A (Announced March 10, 2026)
Sector: AI networks / Network infrastructure HQ: Not publicly established as Miami-based Website: Verified via TechCrunch source Official Source: AI Network Startup Eridu Emerges from Stealth with Hefty $200M Series A (TechCrunch, March 10, 2026)
Eridu emerged from stealth mode on March 10, 2026, announcing a $200 million Series A. The company builds AI network infrastructure, focusing on optimizing and managing AI-driven network systems. The size of the round for a stealth-mode debut signals strong institutional confidence.
Investors: Details per TechCrunch reporting on the Eridu announcement. Public Contact: Not publicly available.
Institutional Investor Implications
The combined $915+ million raised by these seven companies demonstrates robust investor appetite for private technology companies in March 2026. Notable patterns include:

Dual-round structures: Armadin’s combined seed and Series A suggests investors are willing to deploy capital quickly in high-potential companies.
Stealth-mode scale: Eridu’s $200M debut highlights how institutional investors are committing to large pre-launch rounds.
Sector concentration: Cybersecurity (Armadin, Linx Security), AI (Qodo, TENEX.AI, Eridu), and space technology (XBOW) dominate.
a16z presence: Andreessen Horowitz’s involvement in Glimpse underscores continued top-tier VC engagement in consumer-facing technology startups.

Due Diligence Risks
Investors and market observers should consider:

Sizing risk: Rounds exceeding $100M for companies at seed or early Series B stages (Armadin, Eridu, TENEX.AI) carry heightened execution risk.
Technology validation: AI and quantum computing claims require independent technical assessment before investment.
Timeline concentration: Seven major deals announced within a single month create competitive pressure on talent and market positioning.
Funding sustainability: Companies raising in large rounds must demonstrate clear paths to revenue generation and profitability.

Miami Relevance
While only TENEX.AI (Sarasota, FL) has a verified Florida headquarters in this report, the broader implications for Miami include:

Talent competition: Large Florida-based funding rounds create competition for technology talent across the state.
Investment spillover: Significant technology funding in Florida signals broader institutional confidence in the Southeast technology ecosystem.
Industry growth: The presence of a quantum-AI company in Sarasota contributes to Miami’s positioning as a technology hub, though TENEX.AI is not a Miami HQ company.

FAQ
Q: What is the total funding reported in this March 2026 intelligence report? A: Over $915 million combined across seven companies.
Q: Which company is based in Florida? A: TENEX.AI has a verified headquarters in Sarasota, Florida.
Q: Were all companies in this report based in Miami? A: No. Only TENEX.AI has a Florida HQ. The others are not based in Miami or Florida.
Q: What does “historical retrospective” mean in this context? A: This report documents March 2026 funding events published in November 2026. It is not a contemporary April 2026 publication.
Q: Are the funding amounts guaranteed? A: The amounts reflect contemporaneous public disclosures at the time of announcement. Actual final figures may differ.
Read more company and capital-market coverage at MiamiBusiness.com.
Financial Disclaimer
This report is provided for informational purposes only and does not constitute investment advice, financial advice, or a recommendation to buy, sell, or hold any securities. All funding amounts, company details, and investor information reflect contemporaneous public disclosures as of March 31, 2026. This publication does not guarantee the accuracy of all information and recommends independent due diligence before making any investment decisions.

Read More

Emerging Company Intelligence Report — November 2026

This October 2026 investor intelligence report reviews the venture and fintech rounds announced in October 2026 for Miami investors.
October 2026 investor intelligence: Investor Takeaways

TL;DR — November 2026 Emerging-Company Intelligence
Over a thirty-one day period (October 1–31, 2026), eight venture-backed technology and fintech firms completed new financing rounds totalling $326.7 million in disclosed capital. The round sizes alone are notable; the strategic composition is what matters. Volantis (photonics for AI memory, $88 M Series A), North.cloud (cloud-spend intelligence, $60 M Series B), Casap (agentic finance for financial services, $56 M Series B) and Infisical (AI-agent security, $40 M Series B) collectively secured $244 million—74.7% of the month’s total—in infrastructure and security layers that underwrite next-generation AI deployments. Duvo ($32 M Series A, enterprise operations platform), AuxoAI ($20.7 M Series A, forward-deployed AI services), Santé ($15 M Series A, AI operating system for wine and spirits retail) and Mural ($15 M new Series A; $28 M cumulative total funding) round out a cohort whose common thread is the transition from experimental AI to deployed, revenue-generating systems.
For Miami-based investors and corporate-development teams, the signal is clear: capital is flowing to companies that solve expensive, quantifiable bottlenecks in AI inference, cloud cost attribution, agent identity management, and financial-service automation. The profiles below are sourced exclusively from company-issued press releases and official domains; no local Miami presence is claimed or inferred.

1. Volantis — $88 M Series A (October 1, 2026)
Headquarters: San Francisco, California, United States
Volantis closed an $88 million Series A to commercialize its photonic-chip technology, which replaces electronic data movement in AI memory subsystems with light-based interconnects. The company states its proprietary approach “demolishes the AI memory wall”—a widely cited bottleneck where GPUs stall waiting for data transfer between processors and memory. The round positions Volantis to scale manufacturing of its photonic memory modules and expand its engineering team. From an institutional perspective, photonics at the inference layer is a structural bet on the physics limits of silicon interconnects; the addressable market is every data centre that runs large language models or diffusion models at scale.
Key diligence items: The technology is still in the commercialization phase; the press release cites early design-win conversations but no named revenue contracts. Manufacturing scale-up will require significant capex. Investors should monitor Volantis’s supply-chain partnerships and any disclosed pilot deployments with hyperscalers.
Source: Volantis Raises $88M Series A to Demolish the AI Memory Wall with Photonics, October 1, 2026 | Company: volantis.ai

2. Santé — $15 M Series A (October 6, 2026)
Headquarters: France
Santé raised $15 million in a Series A to expand its AI operating system for wine and spirits retail—a niche vertical that combines computer-vision inventory tracking with demand-forecasting and automated replenishment. The company’s platform monitors shelf-level stock in real time, adjusts pricing dynamically based on expiry windows, and generates purchase orders through machine-learning demand models. While the total addressable market is narrower than broader enterprise AI, the margins in premium spirits and wine distribution are significant, and the operational pain points are acute.
Key diligence items: Santé’s vertical focus is both a moat and a constraint. The company has not disclosed named retail partners or recurring-revenue run rates. Investors should evaluate the scalability of the computer-vision hardware stack and the unit economics of onboarding new retail locations.
Source: Santé Raises $15M Series A to Expand the First AI Operating System for Wine & Spirits Retail, October 6, 2026 | Company: sante.ai

3. Duvo — $32 M Series A (October 14, 2026)
Headquarters: London, United Kingdom
Duvo secured $32 million in a Series A to position its platform as a unified operations layer for enterprises. The company’s approach consolidates workflow orchestration, document processing, and data integration into a single “operating system for business operations”—an ambitious category claim. The platform targets mid-market and enterprise customers who currently manage disparate tools for approvals, compliance, and cross-departmental data flows.
Key diligence items: The enterprise-operations space is crowded, with incumbents like ServiceNow and UiPath. Duvo’s differentiation rests on agentic workflow automation and proprietary document-AI capabilities that the release hints at but does not quantify. Due diligence should focus on named pilot customers, gross margins on the SaaS platform, and the velocity of expansion into adjacent workflows.
Source: Duvo Raises $32 Million Series A to Become the One-Platform Enterprises Run Their Operations On, October 14, 2026 | Company: duvo.ai

4. North.cloud — $60 M Series B (October 15, 2026)
Headquarters: New York, United States
North.cloud closed a $60 million Series B to expand its spend-intelligence platform, which unifies cloud-cost attribution, AI-inference-cost tracking, and data-engineering spend optimization into a single dashboard. The company’s core value proposition is helping CFOs and engineering leaders understand—and reduce—the often-opaque cost of multi-cloud and AI-workload deployments. The Series B follows earlier validation from enterprise customers in regulated industries.
Key diligence items: The FinOps / cloud-cost-management market has seen significant consolidation. North.cloud’s differentiation centers on AI-inference-cost granularity, a genuinely new category as models move from experimentation to production. Investors should examine the company’s expansion into adjacent cost domains (e.g., data-lake storage, CDN spend) and its integrations with major cloud providers’ native billing APIs.
Source: North.cloud Raises $60M Series B to Unify Spend Intelligence and Enable Full Automation Across Cloud, AI and Data, October 15, 2026 | Company: north.cloud

5. AuxoAI — $20.7 M Series A (October 20, 2026)
Headquarters: San Francisco, California, United States
AuxoAI raised $20.7 million to build out its “forward-deployed AI” model, in which the company embeds engineering teams directly within client organizations to co-develop and deploy AI solutions tailored to specific workflows. This consultancy-meets-product approach is common in the early days of enterprise AI adoption, as customers struggle to translate internal processes into production-grade automation. AuxoAI’s capital will fund expansion of its delivery teams and development of reusable AI components.
Key diligence items: The forward-deployed model is capital-intensive and scales poorly without productization. The critical question is whether AuxoAI can convert project revenue into recurring SaaS income by productizing its custom builds. Investors should track the company’s conversion metrics and its roadmap for modular AI components.
Source: AuxoAI Raises $20.7M Series A to Build the Forward-Deployed AI Company, October 20, 2026 | Company: auxo.ai

6. Mural — $15 M New Series A / $28 M Cumulative Total (October 20, 2026)
Headquarters: United States
Mural announced a $15 million new Series A, bringing its total cumulative funding to $28 million, to power fintechs and agentic finance applications. The press release frames $28 million as the company’s total raised to date—note, not a new round of $28 million. Mural’s platform provides infrastructure for financial-service automation, including agentic payment orchestration, reconciliation workflows, and regulatory reporting. The company serves fintech customers who need to move money and data across legacy banking APIs and modern payment rails.
Key diligence items: Mural operates in a highly competitive payments-infrastructure layer, alongside Plaid, Stripe, and multiple embedded-finance startups. The press release does not disclose current revenue, customer count, or burn rate. Investors should evaluate the depth of Mural’s banking partnerships and its unit economics on a per-transaction basis.
Source: Mural Raises $28 Million Total to Power Fintechs and Agentic Finance, October 20, 2026 | Company: muralpay.com

7. Infisical — $40 M Series B at $600 M Valuation (October 27, 2026)
Headquarters: United States
Infisical closed a $40 million Series B at a $600 million post-money valuation to “secure the AI-agent economy.” The company develops secret-management and identity-platform technology specifically designed for AI-agent workloads—giving autonomous agents cryptographically verified credentials, encrypted configuration stores, and auditable access controls. As enterprises deploy thousands of AI agents that require machine-to-machine authentication, Infisical’s positioning at the intersection of DevOps security and agent governance is timely.
Key diligence items: The secret-management space includes entrenched players like HashiCorp Vault, Doppler, and 1Password for Teams. Infisical’s open-source heritage gives it distribution advantages, but the press release does not disclose commercial-revenue metrics or enterprise-growth velocity. Due diligence should assess Infisical’s conversion from open-source to paid tiers and its expansion into compliance-driven verticals.
Source: Infisical Raises $40 Million at $600 Million Valuation to Secure the AI-Agent Economy, October 27, 2026 | Company: infisical.com

8. Casap — $56 M Series B (October 28, 2026)
Headquarters: New York, United States
Casap raised $56 million in a Series B to deliver “agentic outcomes for financial services.” The company’s platform uses AI agents focused on fraud detection and dispute management, with stated plans to expand beyond those use cases. The funding will support product expansion, growth beyond fraud and disputes, and sales-team development.
Key diligence items: Casap targets financial institutions where fraud and dispute workflows represent significant operational cost. The press release does not name specific institutional clients or disclose pipeline metrics. Investors should monitor Casap’s progress with regulatory certifications, its security-assurance posture, and the time-to-revenue for new enterprise deals.
Source: Casap Raises $56M Series B to Deliver Agentic Outcomes for Financial Services, October 28, 2026 | Company: casap.io

Market Synthesis
The October 2026 funding window reveals three structural themes for investors. First, infrastructure layers (Volantis photonics, North.cloud spend intelligence, Infisical agent security) command the largest rounds, reflecting the realization that AI’s economic value flows through a stack of supporting technologies. Second, agentic finance is emerging as a distinct category, with Mural and Casap targeting different segments of the financial-services value chain—payment infrastructure on one side, fraud and dispute automation on the other. Third, vertical AI (Santé’s wine and spirits OS, AuxoAI’s forward-deployed model) continues to attract capital despite narrower total addressable markets, because domain-specific workflows offer faster path to revenue and defensibility through proprietary data.
For Miami-based capital allocators, the implications are practical. Infrastructure plays like Volantis and North.cloud offer portfolio exposure to AI’s physical and economic layer with global scale. Agentic-finance companies like Casap and Mural present opportunities for partnerships with Miami’s growing fintech and wealth-management community, even if the companies’ headquarters are elsewhere. Vertical plays require more selective due diligence but can offer asymmetric returns if the target segment is underpenetrated.
Aggregate funding breakdown — eight October 2026 rounds:

Company
Amount

Volantis
$88 M

North.cloud
$60 M

Casap
$56 M

Infisical
$40 M

Duvo
$32 M

AuxoAI
$20.7 M

Santé
$15 M

Mural (new Series A)
$15 M

Total
$326.7 M

Top four (Volantis $88M + North.cloud $60M + Casap $56M + Infisical $40M) = $244 M = 74.7% of total.
All data above is sourced from company-issued press releases and official company websites. No Miami-area operational presence is asserted or implied for any of the companies profiled. This report is published November 7, 2026, with research covering announcements through October 31, 2026.

For more Miami business and investor context, explore ongoing company and financial coverage from MiamiBusiness.com.
Frequently Asked Questions
Q: Why is this report covering October 2026 announcements when published in November?
A: The publication window for the November 2026 Emerging Company Intelligence Report runs October 1–31, 2026. The report was published on November 7, 2026, after the research cutoff of October 31. This timing reflects the standard editorial cycle for monthly intelligence reports.
Q: Are any of these eight companies based in or operating out of Miami?
A: No. All eight companies profiled are headquartered in San Francisco, France, London, New York, and the United States (multiple). The report profiles them for their relevance to Miami-area financial services investors and does not assert any local Miami operations.
Q: What does “agentic finance” mean in the context of these funding rounds?
A: “Agentic finance” refers to AI-driven automation of financial workflows—including payment orchestration, reconciliation, compliance reporting, and fraud/dispute processing—where autonomous agents execute tasks with minimal human oversight. Mural and Casap both operate in this emerging category.
Q: Why was Mural’s $28 M disclosed as total cumulative funding rather than a new round?
A: The Mural press release (October 20, 2026) states $28 million as the company’s total funding to date, comprising a $15 million new Series A added to prior funding. This is not a new round of $28 million. The distinction matters for accurate financial reporting.
Q: Is this financial advice?
A: No. This report is for informational and editorial purposes only. It does not constitute investment advice, a recommendation to buy or sell any security, or an endorsement of any company. All funding figures, valuations, and business descriptions are sourced from publicly issued company press releases and should be independently verified before any investment decision. MiamiBusiness.com and its editors assume no liability for actions taken based on the information contained herein.
The October 2026 investor intelligence findings point to continued funding in AI infrastructure, fintech and enterprise technology.

Report published November 7, 2026. Research cutoff: October 31, 2026. Data sourced exclusively from company-issued press releases at prnewswire.com and verified official company domains. No financial advisory services provided.
Explore MiamiBusiness.com for more local business coverage. For private placement risks, consult the SEC Investor Bulletin.

Read More